- Categories :
- More
3 Things You Can Actually Control About Your Mortgage Rate Right Now
By:
 The McClung Group
| Published 09/21/2026


What can you actually control about your mortgage rate when rates are rising?
You can’t control where mortgage rates go next, but you can influence the rate you may qualify for by focusing on your credit, exploring different loan options, and considering the type of home you buy. Understanding these factors can help you make a more informed homebuying decision instead of simply waiting for rates to change.
If you’re thinking about buying a home, mortgage rates are probably one of the biggest factors on your mind right now. Affordability matters, and when rates start moving higher, waiting for them to come back down can seem like the obvious response.
But rates are currently moving in the other direction.
Mortgage News Daily data shows that the daily 30-year fixed mortgage rate has generally climbed throughout 2026, moving from roughly the low-6% range at the beginning of the year to above 7% in September.
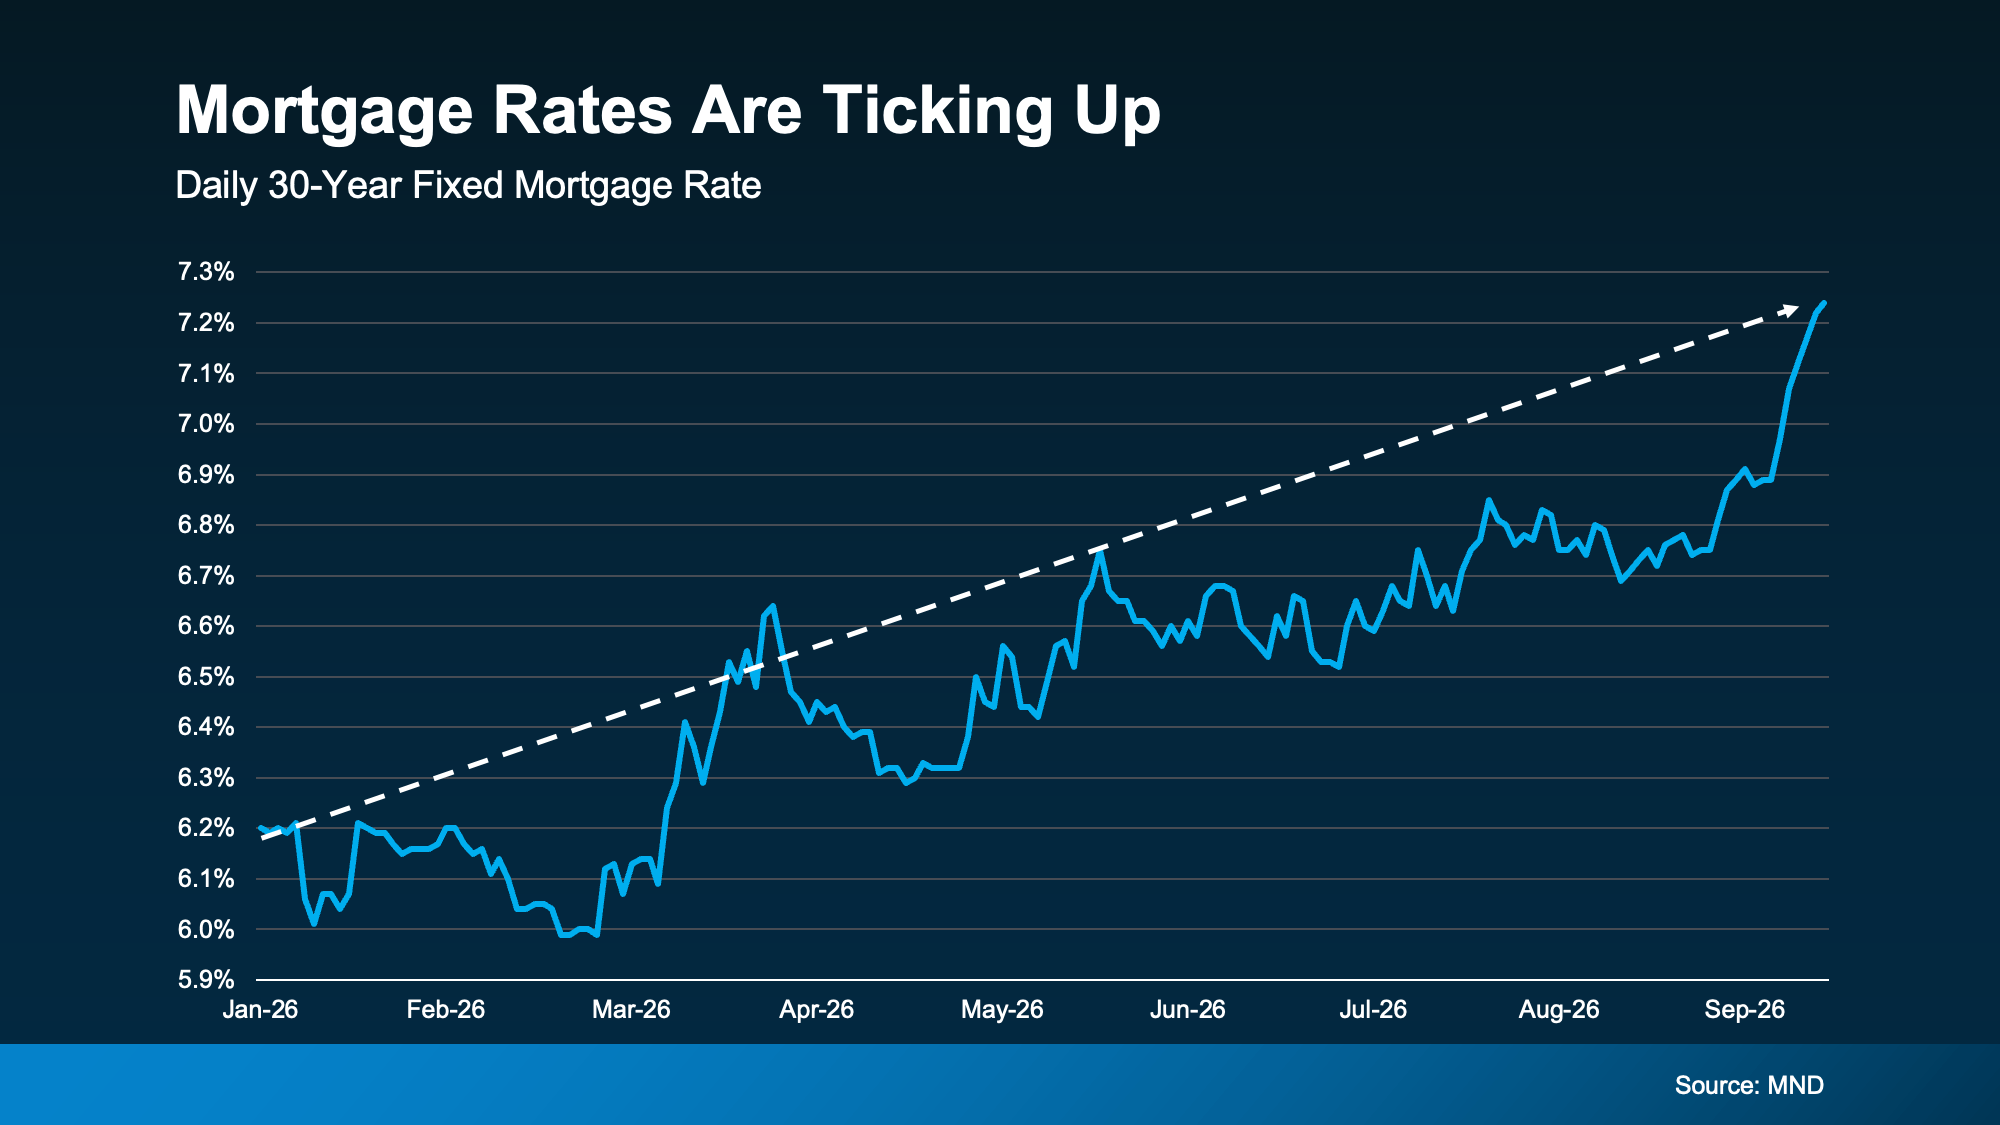
Mortgage rates can be influenced by a number of factors, including economic data, inflation, oil prices, overseas developments, and decisions from the Federal Reserve.
Danielle Hale, Chief Economist at Realtor.com, explains:
“The pressure on mortgage rates was here even before the Fed rate hike, and it doesn’t show signs of relenting. . .”
That may not be the direction prospective buyers were hoping to see. But higher rates don’t mean you have no options.
Rather than trying to predict exactly where mortgage rates will go, it can be more productive to focus on the parts of the equation you can actually influence.
Here are three areas worth paying attention to.
1. Work on Your Credit Score
Your credit score can play an important role in the mortgage rate and loan terms you qualify for.
According to Freddie Mac:
“Generally, the higher your credit score the more options will be available to you, including better loan terms and a lower interest rate.”
That means improving your credit profile could potentially make a difference when it comes time to finance your home.
If you’re planning to buy, knowing where your credit currently stands is a useful starting point. If there’s room for improvement, addressing your credit before purchasing could give you access to additional financing options or better terms.
The important point is that your credit is one part of the mortgage equation you may be able to influence.
You can’t determine what happens to mortgage rates nationally next month. You can, however, pay attention to your own financial position and understand how it may affect the financing options available to you.
And because every buyer’s circumstances are different, it’s important to discuss your individual situation with a qualified lender.
2. Explore Your Mortgage and Loan Options
It’s easy to talk about “the mortgage rate” as though every buyer receives the same number.
That isn’t necessarily the case.
The type of mortgage, loan term, and structure of the loan can all affect the rate and payment associated with financing a home.
Conventional, FHA, VA, and USDA loans each have their own requirements and rates. Loan terms can also vary, including 15-, 20-, and 30-year options.
There’s also the distinction between fixed-rate and adjustable-rate mortgages.
A fixed-rate mortgage maintains the same interest rate over time, while an adjustable-rate mortgage typically begins with a lower rate that can change later.
Bankrate explains:
“. . . rates on fixed-rate loans are typically higher than introductory rates on adjustable-rate loans because the fixed-rate lender takes on the risk that rates could increase during the loan’s term. Likewise, government-backed FHA, VA and USDA loans sometimes have lower rates because they have a government guarantee or insurance that cuts the lender’s risk.”
The lowest initial rate, however, isn’t automatically the right choice for every buyer.
You have to consider your goals, monthly payment, potential rate, loan structure, and any tradeoffs associated with the financing option you’re considering.
This is also why exploring your options can be valuable. Instead of assuming there’s only one mortgage available to you, you can talk with lenders about the different loan structures for which you may qualify.
You may also choose to speak with multiple lenders to understand how available options vary.
The goal isn’t simply to find a low number. It’s to understand the financing structure and how it fits your budget and homebuying plans.
3. Consider a Newly Built Home
Your financing options aren’t the only variable worth considering.
The type of home you buy may also affect the mortgage rate available to you.
Some builders are buying down mortgage rates as an incentive to attract buyers and sell their available homes. For buyers focused on keeping their monthly housing costs manageable, those incentives may make newly built homes worth considering.
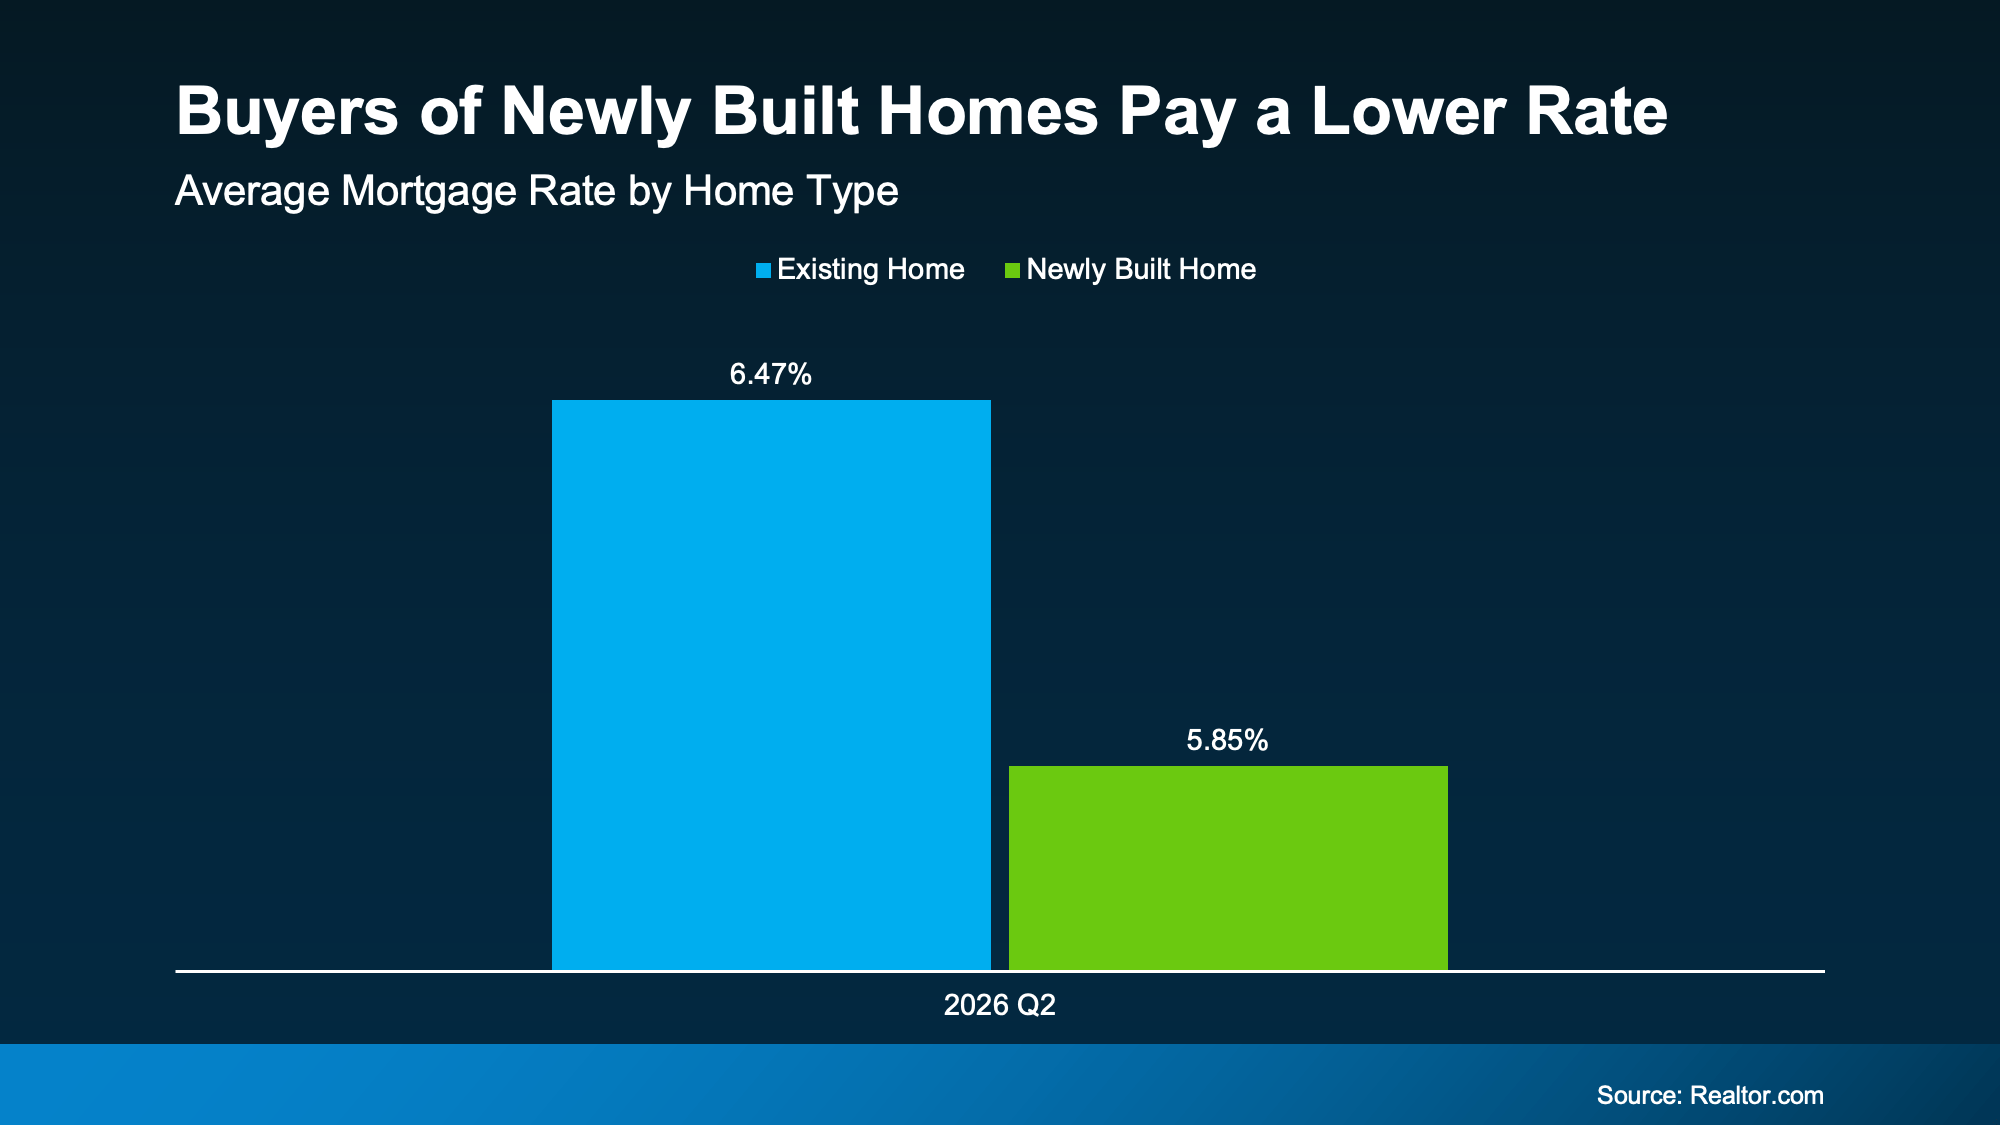
Realtor.com data shows that buyers of newly built homes received a lower average mortgage rate than buyers of existing homes during the second quarter of 2026.
The difference was notable:
- Existing homes: 6.47% average mortgage rate
- Newly built homes: 5.85% average mortgage rate
That doesn’t mean a newly built home will automatically be the right choice for you, nor does it mean every builder or new construction community will offer the same incentives.
It does mean that if your goal is to explore opportunities for a lower mortgage rate, new construction may be worth including in your home search.
Instead of limiting your search to existing homes, you can ask your real estate agent about new construction options and whether builders in the areas you’re considering are currently offering rate incentives.
Having more options gives you more information to work with as you decide which combination of home, price, financing, and monthly payment works for you.
Why Your Homebuying Strategy Matters When Mortgage Rates Change
When rates rise, it can be tempting to put your plans completely on hold and wait for the market to change.
The challenge is that you can’t control when that change happens.
Mortgage rates respond to factors far beyond an individual buyer’s control. Trying to perfectly time those movements can leave you focused on something you can’t influence.
Your own homebuying strategy is different.
You can understand your credit. You can explore different loan structures. You can compare financing options. And you can broaden your home search to include newly built homes where rate incentives may be available.
None of those steps guarantees a specific mortgage rate. They simply help you understand the options available to you based on your individual situation.
That can be particularly important when affordability is one of your biggest considerations.
Buying a Home in The Woodlands? Know Your Options
If you’re considering buying in The Woodlands, your home search doesn’t have to start with trying to predict where mortgage rates will go next.
It can start with understanding your budget and identifying the homes and financing options that may fit it.
At The McClung Group, we’re Realtors serving The Woodlands, and we can help you explore both existing homes and new construction based on what you’re looking for.
Your lender can help you evaluate the financing side of the equation, including the loan programs, terms, and mortgage rates for which you may qualify. On the real estate side, we can help you understand the housing options available and identify properties that align with your priorities.
Together, that information can give you a clearer picture of what buying a home may look like for you right now.
Final Takeaway
You can’t control where mortgage rates go from here, but you don’t have to base your entire homebuying decision on waiting for them to fall.
Focus on the factors you can influence: your credit, your loan options, and the type of home you consider. Newly built homes may also be worth exploring when builders are offering mortgage-rate incentives.
The objective isn’t to predict the market perfectly. It’s to understand your options so you can make a decision that fits your budget and goals.
Ready To Start Your Home Search?
If you’re thinking about buying a home in The Woodlands, connect with The McClung Group.
We can help you explore existing homes, new construction, and the opportunities currently available so you can build a home search around what works for you.
Contact The McClung Group to start your home search today.